Instacart Shopper Rewards

Screenshots
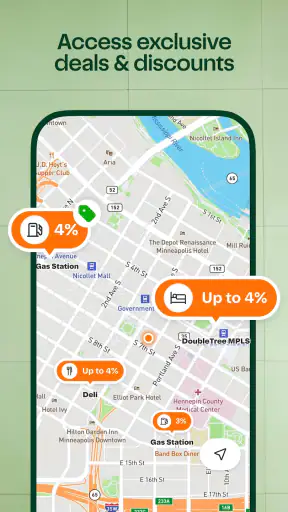
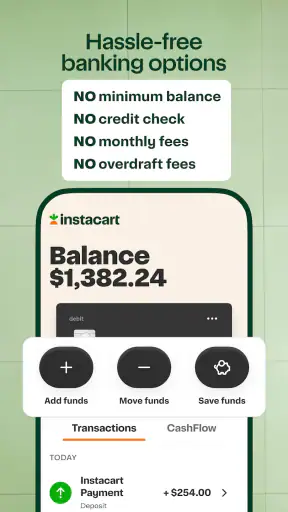
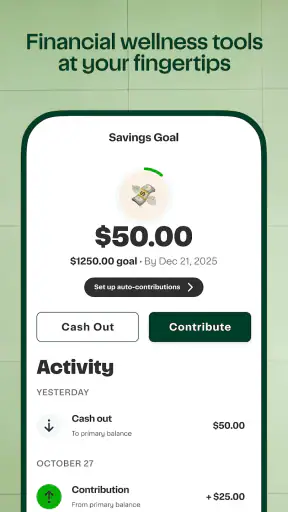
Details
- Rating
- 141.00 reviews
- Version
- 2026.8.2
- Developer
- Branch Messenger
Analysis by Norviv
Instacart Shopper Rewards is a finance app from Branch Messenger aimed at people who earn through Instacart Shopper work and want a debit-card experience connected to that routine. I approached it less like a general banking replacement and more like a focused money tool: useful when your income and spending are tied to deliveries, but not automatically the best choice for every part of your financial life.
The first thing I noticed is how narrow the app’s purpose feels compared with a traditional bank. Its store summary points to a new debit card, while the short description identifies it for Instacart Shoppers. That positioning matters. If you are looking for a simple way to handle shopper-related money, the app has a clear reason to exist. If you want investing, loans, detailed budgeting, or a broad financial dashboard, I would look elsewhere rather than expecting this app to grow into a full personal-finance suite.
It is free to download and carries an Everyone age rating, which makes the initial barrier low. The app was released on August 6, 2025, and its current version is 2026.8.2 for devices running Android 10 or newer. Those details suggest that users on older phones may need to update their device before they can even begin, so checking compatibility first is a sensible step.
What using the app feels like for a shopper
My practical view is that the value comes from keeping shopper-related payments close to the card and account experience rather than forcing every transaction through a separate bank. That can be convenient after a busy day of deliveries. For example, imagine finishing a shift, receiving your shopper earnings, and needing fuel before heading home. A dedicated debit-card setup can make that money feel immediately connected to the work that generated it, instead of mixing it into an account used for rent, subscriptions, and household purchases.
That convenience has a trade-off: a focused financial app can simplify one workflow while making the wider picture less complete. I would not treat it as the only place to manage money until I had personally checked how account access, transfers, card controls, notifications, and support work in everyday use. A debit card is useful only when you can confidently see what is available, recognize each transaction, and regain control quickly if something looks wrong.
The public response is encouraging without being overwhelming. The app holds an average rating of 4.3 from around 500 ratings, with over 100K installs and around 140 written reviews. I read that as a sign of real interest and generally positive reception, not as proof that every shopper will have a smooth experience. Ratings can tell me that the product is working well for many people, but they cannot replace checking whether its account model fits my own habits.
Why the developer and purpose matter
Branch Messenger is the developer, and that is relevant to how I evaluate the app. This is not presented as a neutral budgeting notebook or a generic card-management utility. Its identity is tied to a specific worker and earnings context. That specialization can be a strength because the app does not need to explain a broad collection of unrelated money tools. At the same time, it means I would pay close attention to how the account behaves if my work pattern changes or I stop using Instacart Shopper services.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Before moving money into any specialized financial product, I like to answer a few practical questions inside the app itself: Can I see the current balance without hunting through menus? Are recent card transactions easy to identify? Can I change important account settings without contacting support? Is there a clear way to handle a lost card or suspicious activity? These are not glamorous features, but they determine whether a finance app feels trustworthy during an inconvenient moment.
Trust begins with visible choices
I am cautious about financial apps because the most important experience often happens outside the normal payment flow. Account creation, identity checks, notifications, device access, and card controls all involve sensitive moments. I prefer an app that explains why it needs each piece of information and gives me a clear choice wherever a choice is possible.
With Instacart Shopper Rewards, I would review every permission prompt rather than accepting everything automatically. A finance app should not be judged only by its card design or sign-up speed. I would also inspect the privacy and account sections before relying on it for regular spending, looking for understandable explanations of data use, ways to manage account access, and instructions for closing or securing the account. If those controls are easy to find, that improves my confidence. If they are buried or unclear, I would keep only a limited balance until I understood the arrangement better.
The safest way to test a specialized money app is to start with control, not convenience. I would install it on a supported device, read each prompt, set up the strongest available sign-in protection, and use a small, manageable amount before changing my entire payment routine. That approach does not assume a problem; it simply gives me room to evaluate the service without putting essential bills at risk.
Account controls deserve more attention than the card itself
When I review a debit-card app, I look beyond whether a card can be used at a checkout. I want to know how quickly I can recognize activity and what actions are available when something feels unusual. A good daily workflow should make it easy to distinguish a legitimate fuel purchase from an unfamiliar transaction, especially for shoppers who may make several stops during one working session.
I would turn on every useful transaction alert the app offers and keep notifications readable rather than dismissing them in bulk. If the app provides card-locking or related controls, I would learn where they are before I need them. If it offers ways to update contact details, change sign-in information, or review connected devices, I would locate those screens during setup. These small preparations are more valuable than discovering account controls after a card has disappeared.
Another useful habit is separating work spending from personal spending where possible. Fuel, snacks, parking, and other delivery-related costs can quickly blend together with ordinary purchases. Even if the app does not provide a full expense-management system, I can create my own routine by reviewing transactions after each shift and recording work-related costs elsewhere. That makes the card more useful without pretending it replaces accounting software.
Data-sensitive moments I would handle carefully
Finance apps naturally bring sensitive information into one place, so I would slow down during onboarding. I would avoid setting up the account while connected to an unfamiliar public network, keep the phone’s operating system current, and use a unique password if the app uses one. I would also check that my email address and phone number are correct, because losing access to either can complicate account recovery.
Notifications deserve a privacy check too. A lock-screen message that shows a merchant name or balance can be convenient, but it may also reveal financial activity to anyone who can see the phone. I would adjust the device’s notification preview if necessary. This is a simple user choice, yet it is easy to overlook when the main goal is getting a card working quickly.
I would be especially careful with messages that ask me to provide credentials, verification codes, or personal details. Even when an app is legitimate, scammers can imitate financial support. I would begin support conversations from inside the official app experience rather than trusting an unexpected message. I would also keep records of important account actions, such as a card lock or contact-detail change, so I can explain the sequence clearly if assistance becomes necessary.
A further trade-off concerns convenience versus concentration. Keeping shopper earnings in a dedicated account may make work money easier to follow, but it also creates another financial account to monitor. I would not let the presence of a specialized card make me forget broader responsibilities such as taxes, emergency savings, recurring bills, or a backup payment method. The app can support a workflow; it should not become an excuse to abandon one.
Who gets the most from this app
I see the strongest fit for active Instacart Shoppers who want a debit-card option associated with their shopper income and who prefer a focused experience over a traditional bank’s larger menu of products. It may also suit someone who wants to separate delivery-related transactions from household banking, provided they are comfortable reviewing account activity and maintaining another financial routine.
The app is less compelling for someone who already has a bank account that handles shopper deposits smoothly and provides better budgeting, savings, fraud controls, or customer support. In that case, adding another card could create more work than value. I would also hesitate to recommend it as a primary account for a person who needs a complete financial center with joint banking, long-term savings tools, credit products, or advanced reporting.
It is also not the right choice for anyone who dislikes managing app-based accounts. A specialized debit experience still requires attention: checking balances, reading alerts, protecting the phone, and knowing how to respond to an unauthorized transaction. If you want to visit a branch or speak with a familiar local banker for routine questions, a conventional bank may be a better match even if its shopper connection is less direct.
How it compares with ordinary alternatives
The usual alternative is a regular checking account with a debit card. That option often wins on breadth: one account can handle payroll, bills, savings transfers, and everyday purchases. It may also offer established budgeting tools or a longer history of account-management features. Instacart Shopper Rewards has a more specific appeal because it is built around the shopper context rather than asking a general-purpose bank to fit that use case.
A second alternative is a prepaid or general money app. Those services can be convenient for spending and transfers, but they may not feel connected to the work that generates the money. The advantage here is focus. The disadvantage is that a narrower product may leave me depending on another app for important financial tasks.
I would compare the options using a simple test: Which account makes it easiest to identify income, control card use, recover access, and move money when I need it? The answer may differ by person. A shopper who values separation and a direct work-oriented setup may prefer this app. Someone who values consolidation and mature all-purpose banking may prefer the regular checking account already in use.
A careful setup routine I would recommend
I would begin by confirming that my phone runs Android 10 or newer and that I am downloading the genuine app associated with Branch Messenger. After installation, I would read the account and privacy screens instead of skipping them, record the support path, and review notification behavior. I would also make sure the phone itself has a screen lock and that recovery details are current.
Next, I would use the app for observation before making it central to my finances. I would check how balances and transactions appear, test whether alerts arrive in a useful form, and locate card-management options. I would not wait for an emergency to learn where those controls live. If any screen uses language I do not understand, I would pause rather than guessing, especially when the action concerns transfers, identity, or account closure.
For the first working period, I would keep a backup payment method and avoid routing essential automatic payments through a newly installed account. I would compare the app’s transaction history with my own notes after a shift. This reveals whether the information is clear enough for real-life use and whether the account helps me distinguish shopper expenses from personal spending.
Finally, I would decide whether the app earns a permanent place in my routine. Free access is helpful, but time and attention are also costs. If the card makes shopper money easier to manage and the controls feel transparent, it can be worthwhile. If I find myself constantly switching between services, manually correcting unclear records, or worrying about access, the ordinary bank account may be the more practical answer.
My cautious verdict
Instacart Shopper Rewards makes the most sense as a focused financial companion for Instacart Shoppers, not as an automatic replacement for a full bank. I like the clear connection between the app’s debit-card purpose and the shopper audience. The free price, Everyone rating, current support for Android 10 and newer, and positive average reception make it easy to consider, while the growing install base shows that many people are exploring the service.
Still, I would judge it by control and clarity rather than by convenience alone. Before trusting it with regular income, I would inspect privacy explanations, review permissions, configure alerts, learn the account-recovery process, and keep a backup payment option. Those steps are especially important because financial mistakes are harder to unwind than an ordinary app uninstall.
My recommendation is therefore specific: try it if you actively shop for Instacart and want a dedicated debit-card workflow, but introduce it gradually and keep your broader financial system elsewhere until the app proves dependable for your habits. If your priority is comprehensive banking, advanced budgeting, or one account for every financial obligation, a conventional alternative will probably serve you better. For the right shopper, though, this focused approach can be a useful addition when used with deliberate account controls and realistic expectations.
Frequently Asked Questions
01What is Instacart Shopper Rewards?
Instacart Shopper Rewards is a program designed for eligible Instacart shoppers, offering benefits connected to their shopping and delivery activity. Depending on the current program rules, rewards may include points, discounts, cashback, savings, or other incentives. Availability and benefits can vary by location, shopper status, and promotional periods, so users should review the official terms before relying on a specific reward.
02Who can participate in Instacart Shopper Rewards?
Participation generally depends on meeting Instacart’s eligibility requirements, which may include being an active shopper, completing qualifying orders, maintaining an account in good standing, or working in a supported market. Not every shopper will necessarily receive the same offers. After installing or opening the shopper app, check the Rewards section and your account notifications to see whether the program is available to you.
03How do shoppers earn rewards through Instacart Shopper Rewards?
Rewards are typically earned by completing activities that Instacart identifies as qualifying, such as accepting and successfully completing batches, reaching promotional goals, or meeting other program conditions. The exact calculation may change over time and can differ by region. Before completing an order specifically for a reward, carefully read the offer’s requirements, expiration date, exclusions, and any minimum thresholds.
04Can Instacart Shopper Rewards be exchanged for cash or transferred to another person?
Not necessarily. The way rewards can be used depends on the specific benefit provided by Instacart. Some rewards may be discounts or account credits, while others could have separate redemption instructions, expiration dates, or restrictions. They may not be transferable, refundable, or convertible into cash. Always consult the reward details and official terms displayed in the app before attempting to redeem or share it.
05Is Instacart Shopper Rewards available on both Android and iOS?
The rewards experience is generally accessed through the Instacart Shopper app, which is available for supported Android and iOS devices. However, downloading the app does not guarantee access to every rewards feature, because eligibility, promotions, and regional availability may differ. Keep the app updated, use the official app store listing, and verify that your device and operating system meet Instacart’s current requirements.


